
India’s electric two-wheeler market has crossed another major milestone in 2026, but the headline number tells only part of the story.
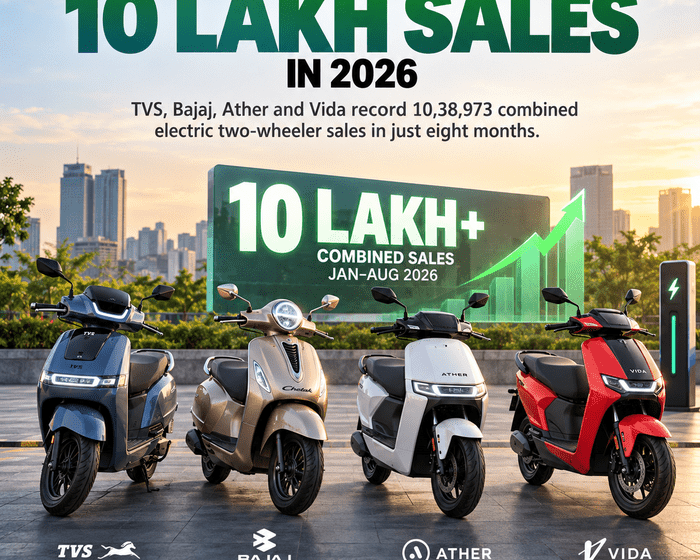
TVS Motor, Bajaj Auto, Ather Energy and Hero Vida together recorded 10,38,973 electric two-wheeler retail sales between January and August 2026, according to Vahan-based data reported by automotive industry publications. The four manufacturers accounted for about 76% of India’s 13.6-lakh electric two-wheeler market during the same period.
The combined volume was 84% higher than the 5,65,635 units registered by these four brands during the first eight months of 2025.
There is another notable benchmark. Their January-August 2026 sales have already surpassed their combined full-year 2025 volume of 9,22,824 units, with four months still remaining in the calendar year.
The numbers point to a significant change in India’s electric two-wheeler landscape: growth is not being distributed evenly across the increasingly crowded market.
TVS leads the four-brand race
TVS Motor was the largest contributor to the 10-lakh milestone, recording 3,56,579 electric two-wheeler retail sales between January and August 2026.
That gave TVS roughly a 26% share of India’s electric two-wheeler market during the period. The company’s electric portfolio, led by the iQube range and supplemented by the Orbiter, gives it products positioned across multiple parts of the mass-market scooter segment.
TVS’s performance is particularly significant because its EV business is being built on top of an established two-wheeler distribution and service network.
The company also had a strong August, with Vahan-based data showing 48,873 electric two-wheelers retailed during the month, up 91% year on year, although August was lower than July’s record monthly figure.
Bajaj is closing the gap
Bajaj Auto followed TVS with 3,05,226 electric two-wheeler sales during January-August 2026.
The Chetak has become the centrepiece of Bajaj’s electric two-wheeler strategy. What began as a relatively premium electric scooter has expanded into a broader range covering different price and customer segments.
The scale of Bajaj’s 2026 registrations also shows how quickly established two-wheeler manufacturers have been able to increase their presence in the EV market.
In August alone, Bajaj recorded more than 41,000 electric two-wheeler registrations in Vahan-based data reported by multiple automotive publications.
Ather’s growth shows the EV specialist still has room to expand
Ather Energy recorded 2,29,099 electric two-wheeler sales in the first eight months of 2026, placing it third among the four manufacturers.
The company’s growth has been supported by the Rizta family, which targets the practical family-scooter market, while the 450 range continues to address customers looking for a more performance-oriented electric scooter.
Ather’s August retail registrations were around 29,000 units, with the company recording more than 51% year-on-year growth according to Vahan-based data.
That combination is important for the broader market. Ather’s numbers suggest that an EV-focused manufacturer can continue to gain volume even as traditional two-wheeler companies expand aggressively into electric mobility.
Vida records the fastest growth among the four
Hero MotoCorp’s Vida brand recorded 1,48,069 electric two-wheeler sales between January and August 2026, making it the smallest of the four by volume but the fastest-growing in percentage terms.
Its reported growth was approximately 151% year on year.
The Vida VX2 has become an important part of Hero’s strategy to build volume in electric mobility. More broadly, Hero MotoCorp’s existing scale and distribution footprint give Vida access to an ecosystem that many smaller EV startups have had to build from scratch.
January-August 2026 sales at a glance
| Brand | Jan-Aug 2026 EV 2W sales | Position among these four |
|---|---|---|
| TVS Motor | 3,56,579 | 1 |
| Bajaj Auto | 3,05,226 | 2 |
| Ather Energy | 2,29,099 | 3 |
| Hero Vida | 1,48,069 | 4 |
| Total | 10,38,973 | — |
Source: Vahan-based retail data reported by Autocar India and Autocar Professional.
Four brands now control three-quarters of the market
The most important takeaway from the numbers may not be the 10-lakh milestone itself.
It is market concentration.
India had around 13.6 lakh electric two-wheeler retail sales between January and August 2026, and TVS, Bajaj, Ather and Vida together accounted for roughly 76% of that volume. Their combined share was around 66% during the corresponding period a year earlier, according to Autocar Professional.
That means approximately three out of every four electric two-wheelers registered during the period came from these four manufacturers.
The remaining quarter was shared by a large number of other manufacturers. Autocar Professional reported that nearly 200 players were listed in the segment, with Ola Electric next among the individual manufacturers at 94,307 units for January-August.
For smaller EV manufacturers, the challenge is therefore changing.
It is no longer enough to develop an electric scooter with competitive specifications. Product pricing, manufacturing scale, dealer reach, service support, financing and customer confidence are becoming increasingly important in converting interest into registrations.
Ola’s position adds another layer to the market shift
Ola Electric’s January-August volume of 94,307 units placed it behind the four leading manufacturers.
That is notable because Ola was one of the most prominent names during the earlier phase of India’s electric scooter boom.
The latest data suggests that the market has become more competitive as traditional manufacturers have expanded their EV portfolios and consumers have gained more choices.
The August numbers reinforce that point. Ola recorded about 13,852 registrations during the month, with its volume declining year on year while several competing manufacturers posted significant growth.
The market is still growing rapidly
The consolidation around four manufacturers should not be confused with a shrinking EV market.
Quite the opposite.
India recorded 1,82,936 electric two-wheeler retail sales in August 2026, according to Autocar Professional. While that was 11% lower than July’s record 2,05,629 units, it represented a 67% year-on-year increase.
The January-August total had already reached around 13.6 lakh units, surpassing the full-year 2025 volume of roughly 13.4 lakh units.
With the festive season still ahead, the industry’s next test will be whether the rapidly expanding market can sustain this pace through the final four months of the year.
What this means for EV buyers
For buyers, the growing concentration has both practical and competitive implications.
The four leading brands offer something that smaller manufacturers may find difficult to match at the same scale: established products, broader service infrastructure and increasing availability across different price points.
That does not automatically make every model from these manufacturers a better choice. Range, charging speed, battery warranty, price, features and local service availability still need to be assessed at the individual-model level.
But the sales data does indicate that buyers are increasingly choosing brands with the ability to operate at scale.
And that could become even more important as electric scooters move further into India’s mainstream two-wheeler market.
The bigger question for the rest of 2026
The four manufacturers have already crossed 10 lakh combined sales. The next question is how much further they can extend that lead.
The broader electric two-wheeler market crossed 13.6 lakh units in eight months, while the top four accounted for approximately 76% of the segment.
If that concentration continues, India’s electric scooter market could increasingly resemble a two-tier industry: a small group of manufacturers operating at significant scale, alongside a much larger group competing for the remaining share.
For EV startups, that raises the importance of differentiation. For established manufacturers, it creates an opportunity to turn existing distribution and manufacturing advantages into further EV growth.
The 10-lakh milestone is therefore more than a sales number. It is an indication that India’s electric two-wheeler race is entering a more scale-driven phase.
INDUSEV TAKE
The interesting part of these numbers is not simply that four manufacturers have sold more than 10 lakh EVs combined.
It is where that growth is coming from.
TVS and Bajaj demonstrate the advantage of bringing EVs into established two-wheeler ecosystems. Ather shows that an EV-first company can continue scaling as mainstream manufacturers enter the segment. Vida, meanwhile, is demonstrating how quickly a major legacy manufacturer can build EV volumes once it starts pushing its electric portfolio.
At the same time, the rise of these four 2 wheeler ev brands does not mean competition has disappeared. The August data shows continued growth from manufacturers such as River, BGauss and Greaves Electric Mobility, while Ola remains a significant player despite its weaker recent performance.
The next phase of India’s EV market may therefore be less about whether electric scooters can find buyers, and more about which companies can consistently turn demand into profitable, scalable businesses.