
| Area | TVS Motor | Bajaj Auto |
|---|---|---|
| EV flagship | iQube | Chetak C35 |
| Affordable EV | Orbiter | Chetak C25 |
| Premium EV | TVS X / higher iQube variants | Chetak C35 |
| August 2026 e2W registrations | 48,873 | 41,018 |
| August market share | 27.1% | 22.7% |
| Core EV identity | iQube family | Chetak family |
| Portfolio strategy | Multiple EV models | Multiple Chetak series |
| Cumulative milestone | 1 million iQube | 7 lakh+ Chetak |
| EV dealer/service reach | 1,000+ EV dealer network; iQube 3,300+ touchpoints cited by TVS | 500+ exclusive Chetak Experience Centres and 4,000+ touchpoints |
| Manufacturing advantage | Large established two-wheeler manufacturing base; EV production expanded at Hosur | Large established manufacturing base; Chetak production integrated into Bajaj’s scooter manufacturing |
| Charging ecosystem | TVS reports ~5,000 public charging points | Focus on integrated Chetak ecosystem and wider service reach |
| Main strategic strength | Portfolio breadth + scale | Chetak brand + rapid portfolio expansion |
| Key EV buyer proposition | Family practicality and multiple battery choices | Design, build, portfolio breadth and established service network |
TVS Motor and Bajaj Auto together accounted for nearly half of India’s electric two-wheeler registrations in August 2026, revealing how quickly established two-wheeler manufacturers have strengthened their position in the EV market.
India’s electric scooter market is entering a different phase.
The biggest story is no longer simply whether electric two-wheelers are growing. They are. The more interesting question is which companies are capturing that growth.
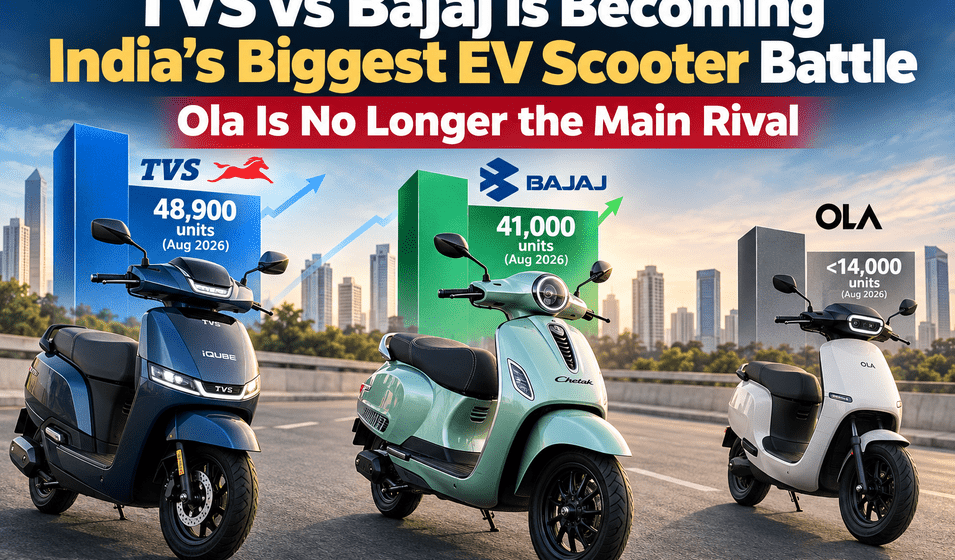
August 2026 registration data provides a clear answer. TVS Motor registered 48,873 electric two-wheelers, giving it a 27.1% market share, while Bajaj Auto recorded 41,018 Chetak registrations, taking a 22.7% share.
Together, the two manufacturers accounted for 49.8% of India’s 1,80,569 electric two-wheeler registrations during the month.
Ola Electric, meanwhile, registered 13,849 units and saw its market share fall to 7.7%, compared with 17.7% in August 2025.
That makes the TVS-Bajaj contest much more important than another monthly sales ranking.
The two companies are demonstrating that the traditional motorcycle and scooter manufacturers can build EV businesses at considerable speed when they combine product variety, manufacturing scale, dealer reach and an existing customer base.
August 2026 EV scooter market: TVS vs Bajaj vs Ola
| Manufacturer | Aug 2026 registrations | Market share | Aug 2025 registrations | YoY change |
|---|---|---|---|---|
| TVS Motor | 48,873 | 27.1% | 25,588 | +91.0% |
| Bajaj Auto | 41,018 | 22.7% | 12,240 | +235.1% |
| Ather Energy | 28,707 | 15.9% | 19,210 | +49.4% |
| Hero MotoCorp (Vida) | 18,977 | 10.5% | ~13,750 | +38% |
| Ola Electric | 13,849 | 7.7% | 19,505 | -29.0% |
| Greaves Electric | 8,614 | 4.8% | — | — |
| River | 5,134 | 2.8% | — | — |
| BGauss | 4,844 | 2.7% | — | — |
| Others | 10,553 | 5.8% | — | — |
| Total | 1,80,569 | 100% | 1,09,435 | +65.0% |
Source: August 2026 retail registration data compiled from MoRTH VAHAN data. Individual historical figures can vary slightly between datasets and reporting cut-offs.
The important number is not just TVS’s lead over Bajaj.
It is the combined 49.8% share.
Almost one out of every two electric two-wheelers registered in August came from these two traditional manufacturers.
TVS’s strategy: Don’t depend on one electric scooter
TVS has taken a portfolio approach to electric mobility.
The iQube remains the core product, but the company has added the Orbiter below it while retaining the premium TVS X above it.
That gives TVS access to multiple price points instead of forcing one scooter to cover the entire market.
The strategy is already visible in the numbers.
TVS’s August model-wise sales data shows 42,882 iQube units and 14,641 Orbiter units, taking the combined volume of the two models to 57,523 units on the reported dispatch measure.
The Orbiter is particularly important because it gives TVS a lower-cost entry into the EV scooter market.
The current Orbiter range offers battery options of 1.8 kWh and 3.1 kWh, with claimed IDC ranges of 92 km and 158 km respectively. TVS lists the Orbiter from around ₹1.04 lakh ex-showroom before applicable incentives on its current website, although pricing varies by variant and location.
The iQube goes substantially further up the range.
TVS currently lists versions ranging from the 2.3-kWh iQube with 114 km IDC range to the 5.3-kWh ST with 212 km IDC range.
That gives TVS something Ola has struggled to maintain consistently: a broad portfolio covering different buyer requirements rather than relying heavily on one product family.
TVS iQube vs Orbiter
| Parameter | TVS iQube | TVS Orbiter |
|---|---|---|
| Positioning | Mainstream family EV | More affordable urban EV |
| Battery options | 2.3–5.3 kWh | 1.8–3.1 kWh |
| Claimed range | Up to 212 km IDC | Up to 158 km IDC |
| Top speed | Up to 82 km/h | Varies by variant |
| Key focus | Family use, range, features | Affordability and practicality |
| Portfolio role | Volume anchor | Entry-level expansion |
Specifications vary by variant. Range figures are certified/IDC figures, not guaranteed real-world range.
Bajaj’s strategy is different: Make Chetak a complete scooter family
Bajaj has taken a different route.
Instead of creating multiple standalone EV brands, it has expanded the Chetak nameplate across several price and performance points.
In April 2026, Bajaj reorganised the range under the C 35, C 30 and C 25 series. The portfolio includes everything from the entry-oriented C25 to the more feature-rich C35 models.
The C25 is particularly significant.
Launched at ₹91,399 ex-showroom in Bengaluru, it uses a 2.5-kWh battery and offers a claimed range of up to 113 km. Bajaj positioned it specifically as a more accessible Chetak for urban users.
The higher C35 models move in the opposite direction, offering a 3.5-kWh battery, up to 153 km claimed range and substantially more equipment.
Bajaj Chetak portfolio
| Model/series | Battery | Claimed range | Top speed | Positioning |
|---|---|---|---|---|
| C 25 01 | 2.5 kWh | 113 km | 60 km/h | Entry/urban |
| C 30 01 | 3.0 kWh | 127 km | 70 km/h | Mainstream |
| C 35 03 | 3.5 kWh | 151 km | 70 km/h | Mid/high |
| C 35 02 | 3.5 kWh | 153 km | 80 km/h | Premium |
| C 35 01 | 3.5 kWh | 153 km | 80 km/h | Flagship |
Specifications from Bajaj’s April 2026 Chetak portfolio update.
The strategy has clearly translated into volume.
Bajaj’s FY2026 annual report records 3,02,674 domestic Chetak sales, compared with 2,60,033 in FY2025. Cumulative Chetak sales crossed seven lakh.
TVS vs Bajaj: The real battle is bigger than scooters
TVS reported a 1,000+ EV dealer network in FY2026 and around 5,000 public charging points, while its June 2026 iQube milestone release cited more than 3,300 touchpoints across 3,000+ cities.
Bajaj’s FY2026 annual report reported more than 500 exclusive Chetak Experience Centres and over 4,000 touchpoints nationwide.
The numbers are not directly comparable because the companies use different descriptions and definitions for their networks. But the broader direction is clear: both are investing heavily in physical distribution and after-sales infrastructure.
Why traditional manufacturers are catching up
This is where the August numbers become more interesting.
An EV startup can develop a compelling product without having decades of experience selling two-wheelers.
Scaling that product nationally is a different challenge.
TVS and Bajaj already understand how to operate dealer networks, manage spare parts, train technicians, finance inventory, handle warranty claims and manufacture vehicles at scale.
That infrastructure becomes particularly important for buyers who are still uncertain about electric vehicle ownership.
A customer buying a ₹1 lakh-plus scooter may want to know a much simpler question than how sophisticated its software is:
“Where will I get it serviced if something goes wrong?”
TVS and Bajaj have an answer to that question because their EV businesses sit inside much larger two-wheeler ecosystems.
Manufacturing scale is becoming an EV advantage
TVS says its EV business delivered 3.71 lakh electric two-wheelers in FY2026, up 33% year-on-year. Its annual report also states that monthly production levels reached 30,000 iQube units and 10,000 Orbiter units.
The company also crossed the one-million iQube milestone in June 2026.
Bajaj’s Chetak business has similarly moved beyond its early-stage EV volumes. Its FY2026 annual report records more than 3 lakh domestic Chetak sales during the year.
Bajaj also has substantial manufacturing infrastructure behind the Chetak programme. Its FY2025 annual report listed 4.8 lakh annual scooter capacity at the Chakan 1/Akurdi facilities, covering Chetak and Yulu products.
The significance is straightforward: once demand increases, companies with established manufacturing and supply-chain systems can potentially respond faster than smaller manufacturers.
Pricing is becoming another battleground
The entry-level EV scooter market has changed considerably.
TVS has moved the Orbiter into the more affordable end of its range, while Bajaj has introduced the C25 specifically to make the Chetak proposition accessible to more customers.
Bajaj launched the C25 at ₹91,399 ex-showroom Bengaluru, while TVS currently lists the iQube family from an effective ex-showroom price of around ₹95,124, subject to variant, location, subsidies and applicable offers.
This puts established manufacturers directly into the part of the market where petrol scooters have traditionally dominated.
And that may be more important than winning the premium EV segment.
The biggest opportunity is converting a conventional scooter buyer who is considering an EV for the first time.
The Ola comparison tells the other side of the story
Ola’s August performance provides an important counterpoint.
The company registered 13,849 electric two-wheelers, down 29% year-on-year. Its market share dropped from 17.7% in August 2025 to 7.7% in August 2026.
That does not mean the EV market itself is weakening.
Quite the opposite.
India’s electric two-wheeler registrations grew 65% year-on-year in August.
The change is therefore primarily about where the growth is going.
TVS grew 91% year-on-year, while Bajaj grew 235.1% in the same dataset.
Ather and Vida also increased their volumes.
The market is becoming more competitive at precisely the time when the overall EV scooter market is expanding.
The bigger shift: EVs are becoming a mainstream two-wheeler business
The August data suggests that India’s electric scooter market is moving away from its first phase.
The early EV race was heavily associated with startups and technology-focused brands.
The next phase is increasingly about scale, distribution, product segmentation and ownership confidence.
TVS has one million iQube customers behind it. Bajaj has crossed seven lakh cumulative Chetak sales. Both companies are expanding their portfolios rather than betting everything on one model.
That changes the competitive equation.
For EV buyers, it also creates more choice.
A customer looking for an electric scooter around ₹1 lakh can now consider products from multiple established manufacturers, while buyers with higher budgets have access to larger batteries, longer claimed ranges and more connected features.
What happens next?
The next few months will be important because the festive season can significantly change two-wheeler registrations.
TVS and Bajaj enter that period with strong momentum, but August alone should not be treated as proof of a permanent market order. Monthly registrations can fluctuate because of inventory, deliveries, supply constraints, regional demand and the timing of purchases.
The more important trend is the one visible over the broader period: traditional two-wheeler manufacturers are no longer treating EVs as a side project.
They are building full product portfolios around them.
And that could be the defining change in India’s electric scooter market.
Indus EV Take
The TVS-Bajaj EV battle is significant because it shows that India’s electric two-wheeler market is becoming a scale game.
Ola helped accelerate the country’s electric scooter adoption, but the competitive landscape has changed. TVS and Bajaj now have the combination of established manufacturing, physical distribution, financing relationships, service infrastructure and increasingly broad EV portfolios.
The August registration data does not prove that one strategy will permanently dominate.
It does show something more important: India’s EV scooter market is increasingly being contested by companies that already know how to sell millions of two-wheelers.
For buyers, that means the next stage of the EV race could be less about which company introduced electric scooters first—and more about who can offer the right product at the right price, with reliable service behind it.